Deep Dives · Auto ABS ·
Who Gets a Payment Extension, and What It Costs
An 84-page Auto ABS deep dive on payment extensions through April 2026 - who servicers extend, how those loans perform two months later, how use is shifting against its pre-COVID baseline, and the loss realized on completed vintages.
84 pages · slides and a PDF · For Premium and Enterprise subscribers
Sample pages
4 of the 84 pages, shown small. Subscribers read every page at full size and download the PDF.
-
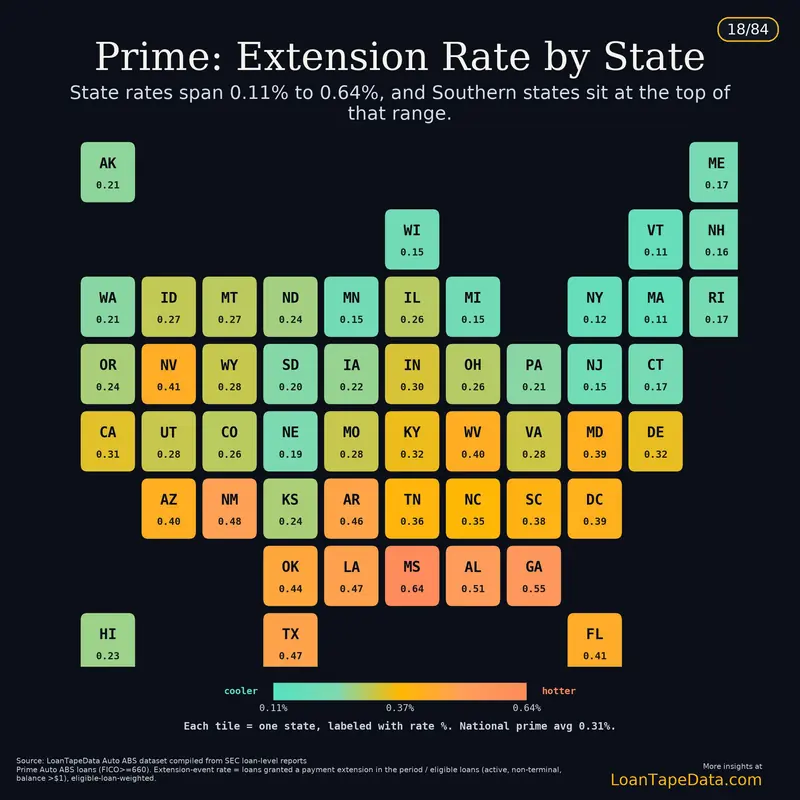
Page 18 of 84
-
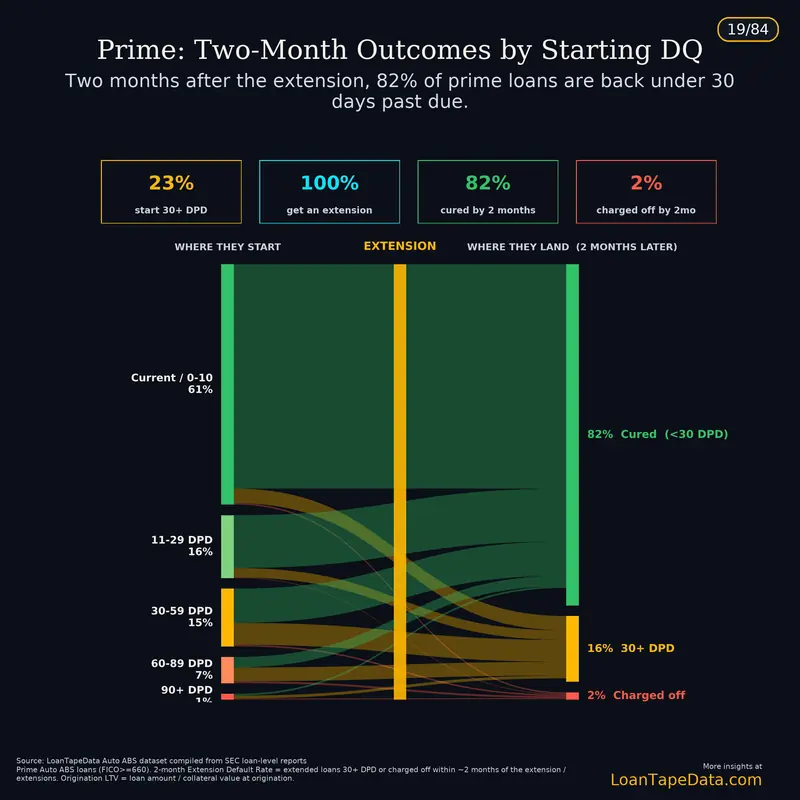
Page 19 of 84
-
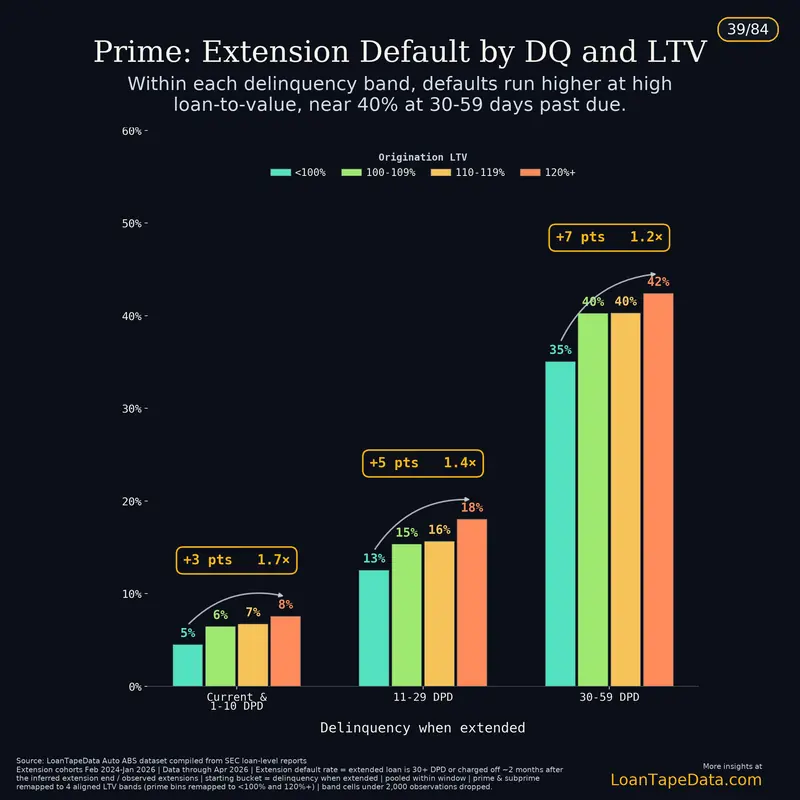
Page 39 of 84
-
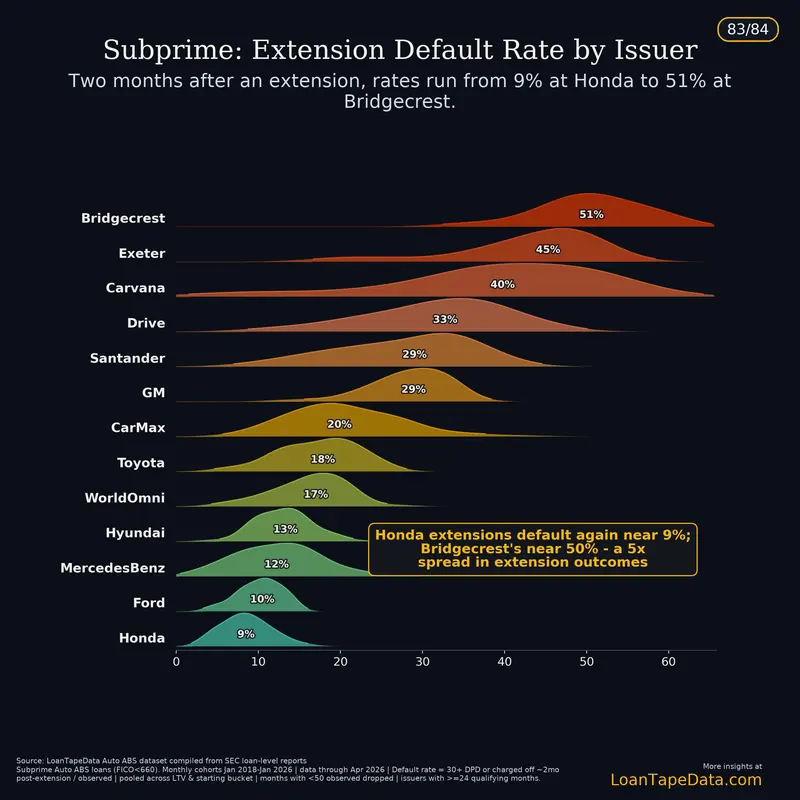
Page 83 of 84
What this deck covers
- Which loans get extended, by delinquency at the extension, origination LTV, payment-to-income, term, vehicle age, geography and issuer, with prime and subprime shown as mirrored sections.
- The 2-month Extension Default Rate: the share of extended loans that are 30+ DPD or charged off about two months later, cut by starting delinquency, LTV and segment.
- How extension use is changing against a 2018-19 baseline, and the trailing-twelve-month share of loans that caught at least one extension.
- Observed loss severity on charged-off loans that were extended first, against those that never were.
- Realized net loss on completed 2018-22 vintages, by issuer and by vintage.
- Issuer screens: who extends most against their own history and against peers, who is moving, and how post-extension outcomes are distributed.
Read the whole deck
Premium and Enterprise subscribers read every page of this deck in the browser and download the PDF, along with every other deck in the library. Premium also adds CSV exports and the AI analyst to the dashboards.